BERKELEY SCHOOL OF BUSINESS, ARTS & SCIENCES

CPA USA – Certified Public Accountant

The CPA (Certified Public Accountant) USA in New York designation, granted by AICPA, is a top certification for accounting professionals. It covers auditing, taxation, and financial reporting.

CPA USA – Certified Public Accountant

Overview

The Certified Public Accountant (CPA) credential in the United States is widely acknowledged as the most prominent accounting certification globally. It is a demanding yet gratifying qualification that can unlock many career prospects. Whether you are commencing your accounting profession or seeking to enhance your current expertise, obtaining a CPA certification can facilitate the realization of your aspirations.

Offered By

AICPA (American Institute of Certified Public Accountants, USA) is the world’s largest member association representing the accounting profession.

Head Office

New York City, New York.

Members

The American Institute of Certified Public Accountants (AICPA) currently represents around 597,000 members worldwide. This membership consists of Certified Public Accountants (CPAs) working across diverse areas, including public practice, business, industry, government, and academia.

Founded In

1887

Card image

Vision & Mission

Vision: The vision of the American Institute of Certified Public Accountants (AICPA) is to empower global professionals and businesses by delivering relevant knowledge, resources, and advocacy in accounting and finance.

Mission: Its mission is to support and advance the CPA profession through education, training, and advocacy, ensuring integrity in financial reporting, serving the public interest, and guiding members in a rapidly evolving business landscape.

What is the Eligibility?

  • Every state has its own criterion but in general, it requires at least a minimum of a Bachelor’s degree (4 years) with Business and Finance Course and Accounting Training Course (subjects in Accounting, Finance, Tax, & Business).
  • 3 years B.Com has bright chances if taxation and audit are studied.

Note: This is a common misconception that you need 120 credit hours. Some states require 24 accounting & 24 business hours, and some states require less.

Arrow Right

Learn More

Who can do?

Card image

Anyone who is interested to learn about the following concepts can pursue
CPA USA – Certified Public Accountant

Auditing and Attestation, Financial Accounting and Reporting, Taxation,
Business Law, Business Analysis and Reporting, Information Systems and Controls,
Tax Compliance and Planning.

Individuals with the following designations:

CFO/CEO, Chairman, Tax Consultants, Policy Makers, Compliance Managers, Inventory Managers, Accountants, Budget Managers, Bankers, AP, AR Manager, Compliance Officers, Financial Analyst, Management Accountant, Finance Controllers, Planning & Strategy Professionals, General Managers, System Auditors, Internal Auditors, External Auditors, Risk Managers, Data Manager, IT Auditor, CIO/CTO, Data Engineer/Data Scientist, Tax Analyst, Tax Compliance Officer, Tax Practice Entrepreneur, Corporate Tax Manager, Full Time & Part-Time Students.

Course Structure

CPA (USA) consists of 3 core subjects and 1 Discipline subject of your choice.

Core 1: Auditing and Attestation (AUD)

It covers key areas such as auditing standards, which include a thorough understanding of Generally Accepted Auditing Standards (GAAS); audit planning and risk assessment, focusing on identifying and responding to risks; and internal controls, highlighting their significance in the audit process. Additionally, you will delve into evidence collection and documentation practices, learn to perform analytical procedures, and understand the various types of audit reports and communication protocols. The outline also incorporates sections on attestation engagements beyond traditional audits.

Core 2: Financial Accounting and Reporting (FAR)

It covers a wide range of topics, including financial statement preparation and reporting, which focuses on the balance sheet, income statement, and statement of cash flows. Additionally, the outline addresses accounting for assets, liabilities, and equity, incorporating both current and non-current classifications. Candidates will also explore financial reporting frameworks, such as GAAP and IFRS, and the requirements for governmental and not-for-profit accounting, ensuring readiness for complex financial reporting issues.

Core 3: Taxation and Regulation (REG)

It covers various areas, including individual taxation, corporate and partnership taxation, emphasizing the tax implications of business structures and transactions. Additionally, the outline addresses tax research and procedures, enabling candidates to understand compliance processes and apply relevant tax laws. The regulation component includes an exploration of business law concepts, ensuring candidates are well-versed in legal frameworks affecting financial and business transactions.

Optional 1: Business Analysis and Reporting (BAR)

It covers business analytics, where candidates learn to interpret financial information and utilize analytical techniques to assess business performance. The outline also addresses reporting standards, emphasizing adherence to GAAP and IFRS. Furthermore, candidates will explore budgeting and forecasting, understanding how to prepare and analyze budgets to guide business strategy.

Optional 2: Information Systems and Controls (ISC)

It encompasses areas such as system design and implementation, where candidates learn about developing and maintaining information systems. The outline also covers information technology (IT) controls, including general and application controls essential for ensuring data integrity and security. Additionally, candidates will explore auditing information systems, focusing on evaluating the effectiveness of controls and assessing IT-related risks.

Optional 3: Tax Compliance and Planning (TCP)

It covers a variety of topics, including individual and business taxation, addressing income, deductions, and credits. Candidates will explore tax planning strategies, emphasizing effective planning to minimize tax liabilities while adhering to legal requirements. Furthermore, the outline discusses tax compliance processes, including filing requirements, deadlines, and the role of tax research in decision-making.

Lecture plan

Core 1: Auditing and Attestation (AUD)
Ethics, Professional Responsibilities and General Principles – 15–25% (2) −
✔Engagement Responsibilities
✔Professional Responsibilities
Assessing Risk and Developing a Planned Response – 25–35% (6) −
✔Planning and Risk Assessment
✔Strategic Planning Issues
✔Internal Control Concepts and Information Technology
✔Internal Control – Sales–Receivables–Cash Receipts Cycle
✔Internal Control – Purchases, Payroll, and Other Cycles
✔Responses to Assessed Risks
Forming Conclusions and Reporting – 10–20% (9) −
✔Internal Control Communications and Reports
✔Evidence – Objectives and Nature
✔Evidence – Sales–Receivables–Cash Cycle
✔Evidence – Purchases, Inventory, Payroll, and Other Cycles
✔Evidence – Key Considerations
✔Evidence – Sampling
✔Reports – Opinions and Disclaimers
✔Reports – Other Modifications
✔Related Reporting Topics
Performing Further Procedures and Obtaining Evidence – 30–40% (3) −
✔SSARS – Preparation, Compilation, and Review Engagements
✔SSAEs – Examination, Review, and Agreed-Upon Procedures Engagements
✔Governmental Audits

Core 2: Financial Accounting and Reporting (FAR)
Conceptual Framework, Standard-Setting and Financial Reporting – 30–40% (3) −
✔Financial Statements
✔Income Statement Items
✔SEC Reporting and Other Accounting Topics
Select Financial Statement Accounts – 30–40% (7) −
✔Cash and Investments
✔Receivables
✔Inventories
✔Property, Plant, Equipment, and Depletable Resources
✔Finite-Lived Intangible Assets and Other Issues
✔Payables and Taxes
✔Noncurrent Liabilities
Select Transactions – 25–35% (5) −
✔Lessee Accounting, Contingencies, and Warranties
✔Equity
✔Consolidated Financial Reporting and Financial Statement Analysis
✔Statement of Cash Flows
✔Governmental Accounting Basics and Not-for-Profit Accounting

Core 3: Taxation and Regulation (REG)
Ethics, Professional Responsibilities and Federal Tax Procedures – 10–20% (2) −
✔Ethics, Professional Responsibilities, and Liability of CPAs
✔Federal Tax Authority, Procedures, Individual Taxation, and Tax-Exempt Organizations
Business Law – 15–25% (3) −
✔Business Organizations
✔Contracts
✔Agency and Regulation
Federal Taxation of Property Transactions – 5–15% (3) −
✔Secured Transactions and Debtor-Creditor Relationships
✔Property Transactions: Basis and Cost Recovery
✔Gross Income and Exclusions
Federal Taxation of Individuals (including tax preparation and planning strategies) – 22–32% (2) −
✔General Business Earnings and Employment Taxes
✔Adjustments and Deductions from AGI
Federal Taxation of Entities (including tax preparation and planning strategies) – 23–33% (3) −
✔C Corporations
✔Flow-Through Entities and Book-to-Tax Differences

Optional 1: Business Analysis and Reporting (BAR)
Business Analysis – 40–50% (6) −
✔Data Analytics
✔Financial Statement Analysis
✔Nonfinancial and Non-GAAP Measures of Performance
✔Costing Fundamentals
✔Costing Systems
✔Budgeting
Technical Accounting and Reporting – 35–45% (7) −
✔Capital Structure
✔Financial Valuation
✔COSO Enterprise Risk Management
✔Derivatives and Risk Mitigation
✔Working Capital Management
✔Economic and Market Influences on Business
✔Revenue Recognition, Hedge Accounting, Leases, and Employee Benefit Plans
State and Local Governments – 10–20% (5) −
✔Business Combinations, Consolidated Financial Statements, and Public Companies Reporting
✔Indefinite-Lived Intangible Assets and Other Topics
✔Governmental Accounting – Methods
✔Governmental Accounting – Funding and Transactions
✔Governmental Accounting – Reporting

Optional 2: Information Systems and Controls (ISC)
Information Systems and Data Management – 35–45% (6) −
✔Introduction to Information Systems and Controls
✔IT Infrastructure
✔Accounting Systems and Blockchain
✔Information Systems Management
✔Data Management
✔Regulations, Standards, and Frameworks
Security, Confidentiality and Privacy – 35–45% (5) −
✔Security: Threats and Attacks
✔Mitigation and Testing
✔Confidentiality and Privacy
✔Incident Response
✔Accounting Information Systems
Considerations for System and Organization Controls (SOC) Engagements – 15–25% (3) −
✔Nature of SOC 1, SOC 2, and SOC 3 Engagements
✔SOC 1 Engagements
✔SOC 2 Engagements

Optional 3: Tax Compliance and Planning (TCP)
Tax Compliance and Planning for Individuals and Personal Financial Planning – 30–40% (4) −
✔Compliance and Planning: Individuals
✔Compliance and Planning: Special Topics
✔Personal Financial Planning
✔Business and Nonbusiness Structures
Entity Tax Compliance – 30–40% (2) −
✔Compliance: C Corporations
✔Planning: C Corporations
Entity Tax Planning – 10–20% (2) −
✔Compliance and Planning: S Corporations
✔Compliance and Planning: Partnerships
Property Transactions (Disposition of Assets) – 10–20% (1) −
✔Disposition of Assets

Learning Methodology

Berkeley offers expertly developed learning materials tailored to meet participants' needs, ensuring comprehensive coverage of the syllabus and optimal exam preparation.

  • ► Tailored Material: Guides are designed to cover the entire syllabus, offering full preparation and deep understanding.
  • ► In-Depth Content: Unlike superficial outlines, our materials provide fully developed theories and concepts, equipping participants with complete knowledge.
  • ► Strategic Study: We help participants prioritize study time by indicating the weight of each topic, allowing efficient focus on crucial areas.
  • ► Difficulty Levels: Topics are labeled as “Awareness” or “Proficiency,” guiding participants to allocate time based on the required depth of knowledge.
  • ► Comprehensive Coverage: Our materials include detailed theory and a glossary of technical terms to clarify complex concepts.
  • ► Effective Learning Techniques: Visual aids and memorization techniques ensure long-lasting retention, helping candidates succeed.

Berkeley’s methodologies equip participants with the essential knowledge and tools for both exams and future success.

Lectures
Lectures
Practice Session
Practice Session
Mock Examination
Mock Examination

Berkeley's performance standards

Evaluates and ensure the quality of the training program and all its deliverables. This is measured through the following indicators:

  • ► Instructors’ experience and style in presenting and explaining topics.
  • ► Variety and balance of teaching methods (such as discussions, case studies, mock exams and videos) used in the course to ensure retention and to match the learning objectives.
  • ► Level of interactivity.
  • ► Feedback from program participants.
  • ► Full compliance with Institute standards and guidelines for preparation and study requirements and methodology.
  • ► Progress reports from the training program provider.
Arrow Right

Learn More

What are the Exam Information?

Exam Format & Duration

* Computer-Based Exams

Part/Module Exam format Exam duration
Core 1: Auditing and Attestation (AUD) MCQ: 78 (Score Weighting: 50%) and 7 Task Based Simulations (TBSs) (Score Weighting: 50%) 4 hours
Core 2: Financial Accounting and Reporting (FAR) MCQ: 50 (Score Weighting: 50%) and 7 Task Based Simulations (TBSs) (Score Weighting: 50%) 4 hours
Core 3: Taxation and Regulation (REG) MCQ: 72 (Score Weighting: 50%) and 8 Task Based Simulations (TBSs) (Score Weighting: 50%) 4 hours
Optional 1: Business Analysis and Reporting (BAR) MCQ: 50 (Score Weighting: 50%) and 7 Task Based Simulations (TBSs) (Score Weighting: 50%) 4 hours
Optional 2: Information Systems and Controls (ISC) MCQ: 82 (Score Weighting: 60%) and 6 Task Based Simulations (TBSs) (Score Weighting: 40%) 4 hours
Optional 3: Tax Compliance and Planning (TCP) MCQ: 68 (Score Weighting: 50%) and 7 Task Based Simulations (TBSs) (Score Weighting: 50%) 4 hours

Exam dates

Core Subjects (AUD, FAR, REG)

Jan 10 – Mar 26

Apr 1 – Jun 25

Jul 1 – Sep 25

Oct 1 – Dec 26

Optional / Discipline Subjects (BAR, ISC, TCP)

Jan 10 – Feb 6

Apr 20 – May 19

July 1 – 31

Oct 1 – 31

Card image

Passing Criteria

To pass each section of the CPA USA exam, you must score at least 75 on a scale of 0 to 99.

EXAM LOCATIONS

The CPA USA exam is available at select Prometric testing centers worldwide, providing convenience for international candidates who do not need to travel to the United States. Key international testing locations include:

✔ Bahrain
✔ Ireland
✔ Nepal
✔ Brazil
✔ Israel
✔ Saudi Arabia
✔ Egypt
✔ Japan
✔ Scotland
✔ England
✔ Jordan
✔ South Korea
✔ Germany
✔ Kuwait
✔ United Arab Emirates
✔ India
✔ Lebanon
Success Stories

Success Stories

“As a strong advocate for education and human development, I commend Berkeley for its exceptional commitment to empowering future leaders. The institution stands as a symbol of excellence, innovation, and opportunity. Students who walk its halls are nurtured with knowledge, values, and vision—qualities that contribute to building a stronger and more prosperous future for our nation.”- H.H. Shaikh Khalifa Al Hamid

Visit Our Alumni

Alumni Benefits

  • ► Exclusive Networking Events: Access invitations to industry-leading events and thought-leadership gatherings featuring renowned speakers.
  • ► Monthly Updates: Stay informed with a newsletter highlighting the latest research, events, and activities from the school.
  • ► LinkedIn Community Access: Join the Executive Education LinkedIn group for networking and professional development opportunities.
  • ► Educational Discounts: Enjoy a 20% discount on open-enrollment programs and access to workshops focused on emerging trends.
  • ► Global Alumni Network: Connect with a diverse alumni community through the Berkeley School’s online network and engage in country and interest groups.

Certified Public Accountant (CPA) Salary: Is It Worth the Investment?

Globally, Certified Public Accountants (CPAs) typically earn significantly more than their non-certified counterparts, with variations based on region and experience. Here are key statistics:

United States: CPAs earn approximately 10–15% more than non-CPAs. Entry-level CPAs earn between $66,000 and $84,000, whereas non-CPAs in similar positions earn around $50,000 to $60,000.

Middle East: In countries such as the UAE and Saudi Arabia, CPAs can earn 15–25% more than non-certified accountants. For example, a CPA in Dubai may earn about AED 300,000 annually compared to AED 200,000 to 250,000 for non-CPAs.

Asia: In financial centers like Hong Kong and Singapore, CPAs earn between $80,000 and $120,000, while non-CPAs earn between $50,000 and $80,000. This reflects a 20–30% salary advantage for CPAs.

Card image

Europe: In the UK, CPAs generally earn around 15% more than their non-certified peers, with entry-level salaries ranging from $55,000 to $80,000, and experienced CPAs earning up to $110,000.

Australia: CPAs can earn between AUD 100,000 and 130,000 (approximately $65,000 to $84,000), with senior CPAs earning even higher salaries.

What you earn

What you earn

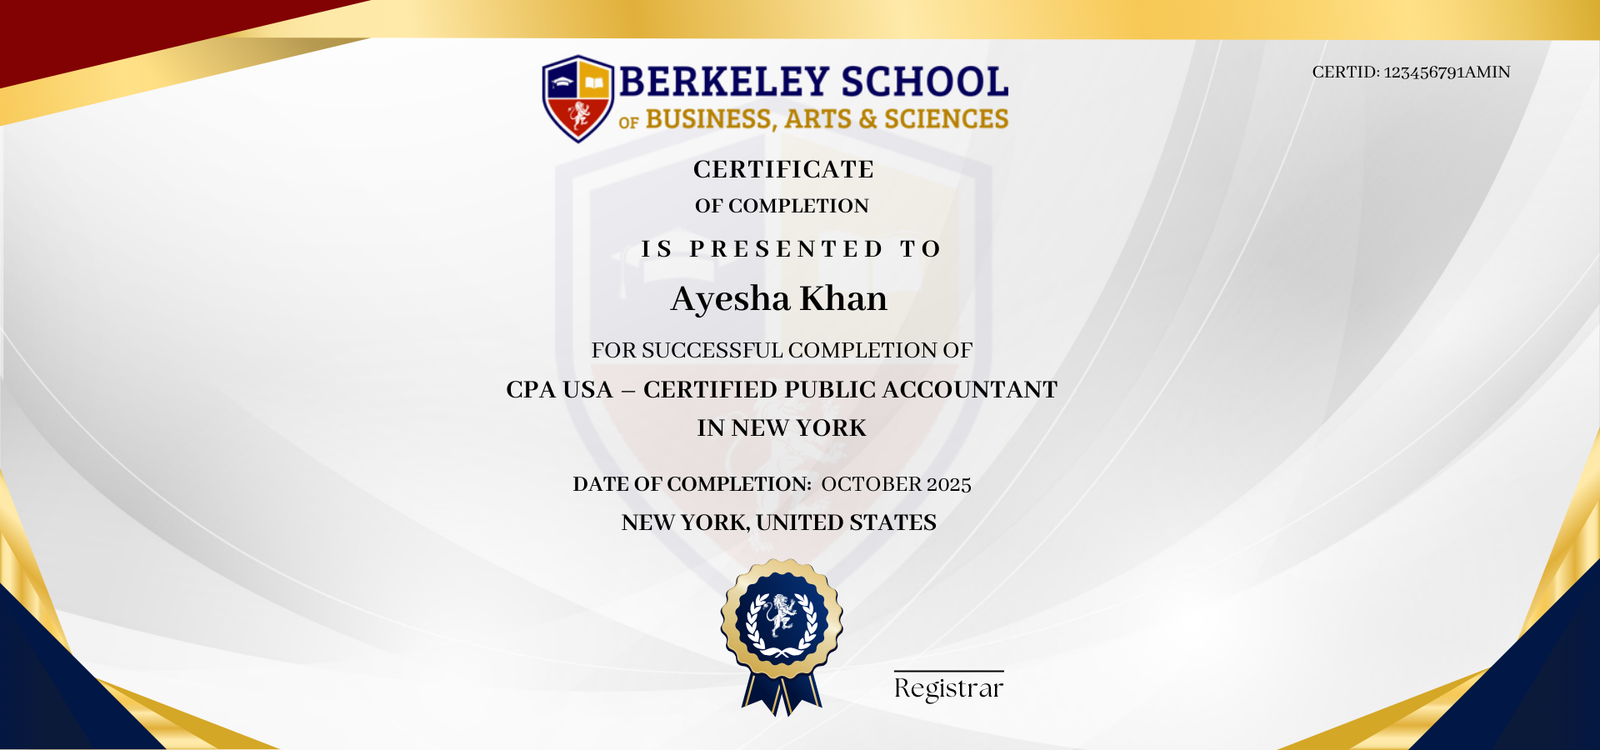
You will get a certificate of completion, which is highly reputed and accepted by employers.

Professional Prestige
Gain a highly respected credential recognized across the accounting profession and beyond.

Career Opportunities
Open doors to a wide range of accounting roles, including senior positions and specialized fields.

Comprehensive Knowledge
Acquire extensive knowledge in accounting, auditing, taxation, and business law.

Regulatory Compliance
Demonstrate adherence to industry standards and regulatory requirements, enhancing your professional credibility.

Networking and Resources
Access a broad network of professionals and resources to support career development and continuous learning.

Contact Us

Facebook Twitter Instagram Linkedin Youtube Tiktok
Cart

Cart (0)